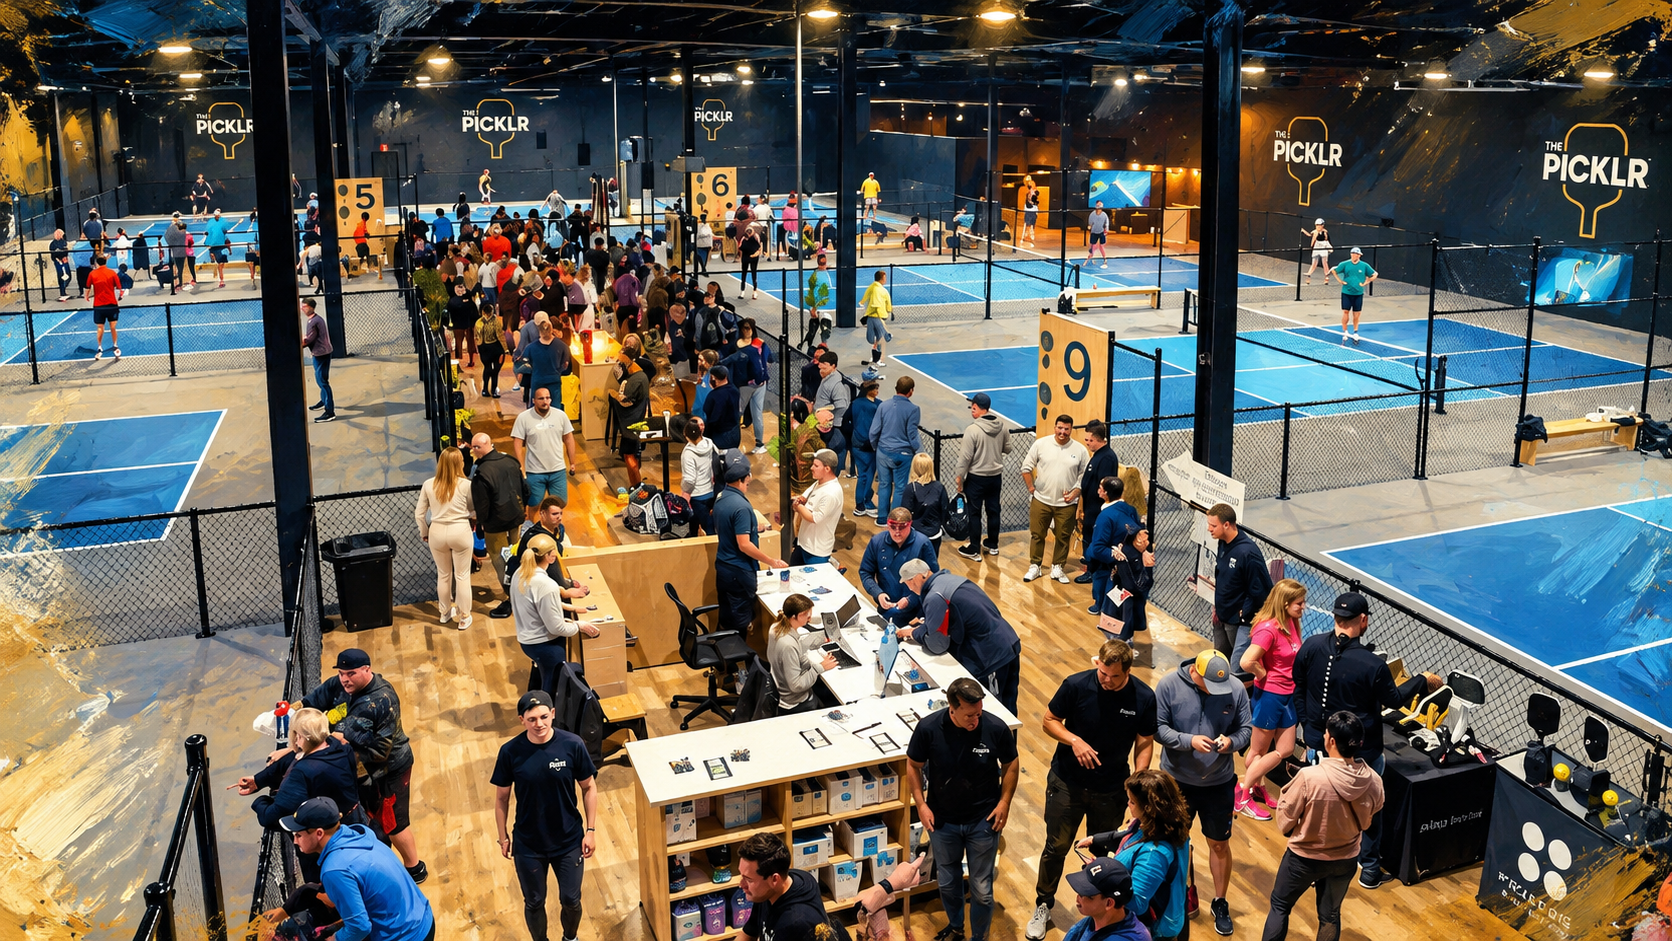
Two US corporate entities behind The Picklr have entered Chapter 11 bankruptcy protection, with a proposed $4.5 million financing commitment offering a possible route forward. Behind the filings lie bigger questions about franchise economics, expensive property commitments and whether rapid expansion can translate into sustainable club businesses.
Key Takeaways
- Picklr, Inc. filed for Chapter 11 on 9 October 2026, followed by Picklr Clubs, Inc. on 10 October. Both proceedings are listed in the Northern District of Texas.
- The Picklr has announced a proposed $4.5 million financing commitment from investors led by an existing franchisee, subject to court approval.
- A reported August balance sheet for Picklr, Inc. showed approximately $915,000 in assets and $2.39 million in liabilities. These are not consolidated figures for the franchise network.
- The company’s 2026 franchise disclosure figures show estimated initial investment costs of approximately $1.25 million to $2.08 million for a location.
- Corporate bankruptcy does not automatically close independently operated clubs, but it raises questions about franchise support, contractual obligations and long-term financial sustainability.
For much of its recent history, The Picklr has presented a compelling vision of pickleball’s commercial future: dedicated indoor courts, recurring membership income, a recognisable national brand and a franchise network capable of expanding across the United States and into international markets.
That vision has attracted investment, franchise partners and attention from high-profile figures. In March, World Pickleball Magazine reported on Nick Kyrgios’s investment and ambassador agreement with The Picklr, examining how professional athletes were beginning to see commercial opportunities in the infrastructure surrounding the sport.
As recently as September, another part of the network’s international ambition was taking shape in Japan. The opening of PICKLR TOKYO TOYOSU, a seven-court facility operated by Nippon Pickleball Holdings, provided a visible example of the brand’s appeal beyond North America.
Now, the US corporate business faces a very different challenge.
On 9 October 2026, Picklr, Inc. filed for Chapter 11 bankruptcy protection in the United States Bankruptcy Court for the Northern District of Texas. Picklr Clubs, Inc. followed with a separate filing on 10 October.
The filings do not mean every Picklr club has closed, nor do they establish that the indoor pickleball business model is fundamentally unworkable. They do, however, place the finances behind one of the sport’s most ambitious franchise networks under a level of scrutiny that expansion announcements alone could never provide.
The central question is no longer how many facilities The Picklr can open. It is whether the financial structure supporting those facilities can be made sustainable.
Two Corporate Filings, Not a Nationwide Shutdown
The distinction between corporate restructuring and the operation of individual clubs is essential to understanding the story.
Picklr, Inc. filed under case number 26-34687 on Friday, 9 October. Picklr Clubs, Inc. filed under case number 26-34690 the following day. Both are listed in the official restructuring information portal maintained by Omni Agent Solutions.
The published docket entries identify the petitions as Chapter 11 filings under Subchapter V, a restructuring framework available to qualifying smaller businesses.
Chapter 11 allows a business to seek court protection while attempting to reorganise its financial obligations. It is different from an immediate liquidation, although it does not guarantee that a company will survive or that all existing operations will continue unchanged.
The Picklr has stated that independently owned franchise clubs remain operational and that memberships, court bookings and programmes are continuing as usual.
That reassurance matters to players who may have paid in advance for memberships, coaching or other services. It should nevertheless be understood as the company’s position rather than an independently verified guarantee covering every location.
Franchise systems involve multiple legal and commercial relationships. Individual clubs may be owned by separate companies, each responsible for its own employees, property leases, financing arrangements and day-to-day operations.
A corporate bankruptcy filing does not automatically place those independently owned businesses into bankruptcy. Equally, a financially healthy individual club does not necessarily mean that its franchisor has sufficient resources to maintain every support service and contractual commitment.
The distinction becomes especially important when a franchise network has expanded rapidly and its corporate organisation has assumed obligations connected to individual locations.
What the Reported Financial Figures Reveal
The financial position disclosed in reporting on Picklr, Inc.’s bankruptcy petition provides a clearer indication of why restructuring has become necessary.
According to an analysis published by the International Association of Pickleball and Padel Facilities, a balance sheet attached to the petition and dated 31 August 2026 listed approximately $915,000 in assets against $2.39 million in liabilities.
The reported figures included around $70,000 in bank accounts, a $1.5 million line of credit and approximately $845,000 outstanding on a bank loan.
These numbers require careful interpretation. They concern the entity and reporting date identified in the filing, not the consolidated financial position of every club operating under The Picklr brand. They also should not be presented as the company’s exact cash position on the October filing date.
Nevertheless, the relationship between reported assets, liabilities and immediately available cash suggests why the corporate business has limited room to manoeuvre.
Where financial obligations substantially exceed available resources, a company may become vulnerable to creditor demands, delays in expected income or commitments that cannot be reduced quickly.
The published analysis also identified seven unsecured claims associated with guarantee obligations, with a combined stated amount of approximately $783,000.
All seven were classified as contingent, unliquidated and disputed. Those descriptions matter because the figures do not represent liabilities finally determined by a court or necessarily accepted by the company.
They do, however, point towards an important aspect of the franchise structure: the potential financial connections between corporate entities and the obligations of individual club operators.
Why Lease Guarantees Matter
Opening an indoor pickleball facility usually involves securing a suitable building, often under a long-term commercial lease.
For a new franchisee without an established trading history, landlords may require additional security before agreeing to substantial property commitments. A corporate guarantee can help an operator obtain premises by providing a measure of support from the wider franchise organisation.
That support may be commercially useful, but it can also create risk.
If a local operator encounters financial difficulty and cannot meet its obligations, a guarantee may expose the supporting corporate entity to claims, depending on the precise contractual terms.
The Picklr’s franchise documentation has included lease-guarantee arrangements, although the obligations applying to individual operators may differ.
The presence of disputed guarantee claims in the corporate bankruptcy reporting makes this an important area for further scrutiny. It does not establish the full value of every guarantee, nor does it prove that all potential claims will ultimately become payable.
The broader concern is structural. When a franchise business supports rapid expansion through commitments connected to individual properties, difficulties at local clubs can potentially create financial pressure elsewhere in the network.
That is why the distinction between opening a facility and establishing a profitable, sustainable business matters so much.
The Proposed $4.5 Million Financing Commitment
The Picklr has announced that an investor group led by an existing franchisee has committed $4.5 million in proposed financing to support the restructuring, subject to court approval.
The involvement of a franchisee is noteworthy because an operator within the network has direct experience of the costs and challenges associated with running a club.
Such experience may provide useful insight into the practical requirements of the business, including court utilisation, membership income, staffing and property costs.
It would, however, be premature to conclude that the investment automatically resolves the company’s difficulties or establishes a new operating strategy.
A financing commitment is not the same as cash already received and available without restriction. Its ultimate value depends on court approval, the detailed terms, any conditions attached and the financial needs of the restructuring.
Nor does the headline figure alone establish whether the funding will be sufficient to address existing obligations and support continuing operations.
The proposed financing offers a possible route forward. The court process and the company’s subsequent operating performance will determine whether it becomes a durable solution.
Franchise Expansion Is Not the Same as Club Profitability
The Picklr’s commercial strategy has been closely associated with the pace of its franchise expansion.
Figures indexed from its May 2026 Franchise Disclosure Document show that the number of franchised outlets increased from 22 at the beginning of 2025 to 56 at the end of that year.
That is a substantial increase, but it does not answer the most important financial question: how many locations were generating sustainable profits?
A franchise territory sold is not an operating facility. An operating facility is not necessarily an established business. And a club generating substantial gross revenue may still be unprofitable after its costs are taken into account.
The indexed 2026 franchise disclosure figures provide useful context.
Only 12 franchised outlets were included in the disclosed sample of clubs that had operated for at least one full year. Their average annual gross revenue was $962,734, with a median of $938,176.
The highest reported figure was $1,843,170, while the lowest was $498,014.
These figures show that some established Picklr locations were capable of generating significant sales. They do not show the profitability of those locations or establish that newer facilities would achieve comparable results.
The sample was also relatively small compared with the number of franchised outlets reported at the end of 2025.
That limitation is particularly relevant when a business is expanding into different cities, property markets and customer bases. A successful facility in one location does not guarantee that the same model will work under substantially different commercial conditions.
The Financial Demands of an Indoor Pickleball Club
The Picklr’s 2026 franchise disclosure figures put the estimated initial investment for a single location at approximately $1.25 million to $2.08 million, with an initial franchise fee of $60,000.
Those are significant financial commitments before an operator has established a mature membership base.
A purpose-built indoor facility may require substantial spending on court surfaces, lighting, fit-out, equipment, reception areas, changing facilities and other infrastructure. The operator must then support the business through regular income from memberships, court hire, coaching, leagues, tournaments and events.
None of those revenue streams is guaranteed.
The most difficult feature of the model is that many operating costs remain relatively fixed. Rent, insurance, utilities, maintenance and financing commitments continue whether courts are fully occupied or largely empty.
Staffing and programming costs must also be managed, while a franchisee has additional contractual obligations to the wider network.
Published analysis of The Picklr’s franchise documentation identifies a 7% royalty on gross revenue and a national marketing contribution of at least 2%, with additional charges potentially applying under particular arrangements.
To illustrate the effect, a hypothetical club generating $1 million in annual gross revenue would pay $70,000 in royalties at 7% and at least $20,000 in marketing contributions at 2%.
That amounts to $90,000 before rent, wages, utilities, financing, maintenance and other operating expenses.
This is an illustrative calculation, not a statement about the actual financial performance of any particular Picklr club. Individual executed agreements determine the fees and obligations that apply.
The calculation nevertheless demonstrates why strong revenue figures cannot be treated as evidence of profitability.
A facility may appear busy during evenings and weekends while still carrying substantial unused capacity during quieter periods. If the income generated across the full week is insufficient to cover its costs, a popular club can remain a financially difficult business.
The essential commercial question is not simply whether people want to play pickleball. It is whether enough customers will pay enough, often enough, to support the particular facility and its financial commitments.
Franchisee Difficulties Before the Corporate Filings
The October bankruptcy petitions followed a period of uncertainty surrounding The Picklr’s corporate operations and parts of its franchise network.
Reports in September described corporate staff reductions and financial pressure, while several individual facilities experienced closures or changes in operating arrangements.
Those developments should not be attributed automatically to a single cause.
Individual clubs may face different challenges, including local competition, high property costs, insufficient membership income or changes involving landlords.
One particularly relevant example is Goleta, California, where a former Picklr facility continued under the independent name The Grove Pickleball.
The distinction is important because a club leaving a franchise network does not necessarily mean that the local demand for pickleball has disappeared.
In some circumstances, a facility may remain viable while its owner seeks a different commercial structure or greater operational flexibility.
That raises a difficult but necessary question for the franchise model: what financial and operational value does the corporate relationship provide to an individual club, and does that value justify the associated costs?
It is not a question that can be answered from a single location. But it becomes increasingly important when a network’s corporate organisation is seeking bankruptcy protection.
A Separate Franchisee Bankruptcy Adds Complexity
The corporate proceedings are not the only bankruptcy cases involving businesses connected to The Picklr.
On 24 September, 3 Strand Holdings LLC and 12 related entities filed separate Chapter 11 proceedings in the Middle District of Florida.
The group is associated with several Picklr-branded locations, including Burlington, Danvers, Exton, Newark and Westbrook.
Those debtors are separate from Picklr, Inc. and Picklr Clubs, Inc., and their proceedings should not be conflated with the October corporate filings.
However, reporting on the Florida case describes a dispute involving a proposed asset purchase agreement with Picklr Clubs, Inc., together with questions about leases, contract assignments and the parties’ respective obligations.
The parties have advanced competing positions. The available reporting does not establish that a court has finally resolved those disputes or determined that one side is responsible for every contested obligation.
A hearing had been listed for 20 October, although its status and the effect of the subsequent corporate filings will require continued monitoring.
The dispute illustrates the complexity of a franchise network in financial distress.
An individual club operator may have obligations to landlords, lenders, suppliers and employees, while also maintaining agreements with its franchisor. Where asset transactions or corporate guarantees are involved, financial difficulties can produce overlapping disputes across multiple businesses.
Resolving those relationships may prove as important as obtaining new financing.
What Happens to Members and Existing Clubs?
For players, the most immediate concern is likely to be whether their local courts remain available.
The Picklr has said that clubs remain open and that independently owned franchise operators are continuing normal activities, including memberships, bookings and programming.
That position offers reassurance, but the legal and financial circumstances of individual locations may differ.
A club with a strong membership base, manageable property costs and healthy cash flow may be able to continue operating successfully while the franchisor restructures.
A facility already experiencing financial difficulties may face greater uncertainty, particularly if its business depends on corporate support or contractual arrangements that could change.
Members should therefore look to their own club operators for location-specific information rather than assume that the corporate filing has the same consequences everywhere.
For franchise owners, the questions extend to the future of technology, marketing, training, operating systems and other services supplied by the corporate organisation.
Whether the restructuring preserves those functions, changes their delivery or alters franchise relationships will be an important measure of its success.
Why The Picklr’s International Expansion Matters
The timing of the filings is especially striking when considered alongside the brand’s international activity.
On 25 September, PICKLR TOKYO TOYOSU opened in Japan, with general visitor access beginning in October.
As WPM’s Japan correspondent Fabrizio Lavezzari reported from the opening, the facility provides seven dedicated indoor courts in a market where players have often relied on shared or multipurpose spaces.
The venue is operated by Nippon Pickleball Holdings, and its existence should not be interpreted as evidence that the Japanese operator is included in the US bankruptcy proceedings.
Instead, the contrast demonstrates how the brand’s commercial appeal and the financial condition of its US corporate entities can be two different stories.
A franchise or licensing concept may continue to attract interest internationally even while its originating business is restructuring.
The question for those operators is how the restructuring could affect brand relationships, support services and future contractual arrangements, rather than assuming their local businesses are automatically insolvent.
Does This Mean Indoor Pickleball Is in Trouble?
The Picklr’s bankruptcy will inevitably prompt questions about the viability of dedicated indoor pickleball facilities.
But it would be misleading to treat the financial difficulties of one franchise organisation as a verdict on the entire sector.
Indoor clubs operate under different ownership models, property arrangements and cost structures. Some are independent facilities, while others are part of franchises, leisure centres or multi-sport businesses.
A modest club operating from an affordable building may have very different economics from a large facility carrying substantial fit-out debt, high rent and recurring franchise fees.
The relevant question is therefore not whether indoor pickleball can work, but which business models can consistently convert participation into sustainable income.
Demand for the sport creates an opportunity. It does not guarantee that any particular facility can attract enough paying customers at prices sufficient to cover its costs.
Even popular clubs must manage the difference between peak and off-peak demand, the costs of maintaining their facilities and the challenge of keeping members engaged over time.
Those are ordinary commercial realities, but they become especially significant when a business model requires seven-figure initial investment.
The Picklr’s restructuring makes those realities more visible. It does not establish that they cannot be overcome.
The Next Test Is Sustainability, Not Expansion
The Picklr now faces a more demanding measure of success than the number of franchise territories sold or new facilities announced.
Its immediate challenge is to navigate Chapter 11, address creditor obligations and establish whether the proposed $4.5 million financing can provide sufficient support for a viable restructuring.
The separate corporate filings also make it important to establish which entities are responsible for particular assets, liabilities and operating functions.
Beyond the legal process lies the commercial question that will determine the company’s future.
Can the corporate organisation provide the services its franchisees need without assuming financial commitments that exceed its resources? And can individual clubs generate enough income, after rent, staffing, financing and contractual fees, to justify the substantial investment required to open them?
The answers will matter to existing operators, prospective investors and the wider indoor pickleball industry.
The Picklr has helped establish dedicated indoor facilities as a recognisable part of the sport’s commercial landscape. Its current difficulties do not erase that contribution, and Chapter 11 does not automatically mean the business has reached its end.
But the filings do mark a significant change in how its progress should be assessed.
The number of clubs opened can demonstrate ambition. Revenue can demonstrate customer demand. Neither, on its own, demonstrates financial sustainability.
The next chapter will be shaped by court decisions, financing arrangements and the performance of the clubs themselves.
For The Picklr, the question is no longer how quickly the network can expand.
It is whether the business behind that expansion can endure.
Further Reading
- Nick Kyrgios Invests in The Picklr as Athlete Equity and Facility Growth Converge
- The Dream Becomes Reality as PICKLR Opens in Japan
- The Picklr’s Chapter 11 restructuring information and court dockets
- The Picklr’s 2026 franchise disclosure figures

Chris Beaumont
Founder and Editor-in-ChiefChris Beaumont is the founder and Editor-in-Chief of World Pickleball Magazine. Chris follows the global game closely, reporting on the latest news, developments, stories and tournaments from all five continents. He also hosts the World Pickleball Podcast, interviewing people at…
View All Articles →